We know superannuation can seem boring, but putting good strategies in place now could make a big difference to your future. And getting your super sorted doesn't need to be time consuming or hard work. Here are some quick and easy tips to help get you on your way.
1. Find lost super
Did you know that there's more than $13 billion of lost super in Australia? That's a lot of money and there's a chance some of it's yours. It's easy to search for your money via SuperSeeker, the Australian Taxation Office's (ATO) online search tool. After all, if you lost a $100 note, you'd spend at least a few minutes looking for it, so why not spend a little time finding your lost super? Go to www.ato.gov.au and follow the links to SuperSeeker to search for your lost super.
2. Consolidate yoru super and save on fees
And once you've found any lost super, don't burden yourself with multiple fees and bundles of paperwork by having several super funds. It makes sense to roll it all into one super fund. Fewer fees and less paperwork!
3. Exercise your right to choose
So now that you have all your super in one place, make sure you choose where it's invested. Super funds nowadays have many different investment options that members can choose from. So no matter what stage of life you're at or what your investment goals are, your super fund will have an investment option that's right for you. Alternatively, speak to your financial adviser for professional help and they'll be able to assist you in deciding on an investment option that suits your needs.
4. Make the most of profesional advisers with the right expertise
After you've done all this, and if you'd still like an extra helping hand getting your super sorted, why not use the professional services of a financial adviser from Intellichioce? For a completely low fee, our team of qualified financial planners can help you grow your wealth and help you get on track to a comfortable financial future. Call 1300 55 10 45 for an obligation free financial meeting with one of our financial advisers.
5. Ensure you're insured
Life insurance is unlikely to be a big priority if you don't have a family, but what would happen if you couldn't work due to injury? You probably have insurance cover as part of your super, but you should check that it's enough. It's also worth noting that income protection premiums are generally cheaper if taken out through your super, but again, make sure that it's enough and meets your requirements.
For financial advice on superannuation or insurance, speak to a financial planner at Intellichoice today on 1300 55 10 45 or visit www.intellichoice.com.au for details on the various services offered.
Sunday, October 10, 2010
Tuesday, July 20, 2010
Cash investments popular among investors
Self managed super fund (SMSF) investors have led the market in adopting online savings accounts and term deposits with 29% per cent of self managed super assets moving to cash between 2008 and 2009 - during the GFC.
Post GFC, cash is still maintaining its popularity among some investors. A UBank survey of customers in March 2010 revealed that a third of SMSFs have more than 50% of their funds in cash.
Some of the returns available on cash rates have been quite attractive with the Reserve Bank of Australia increasing interest rates.

Wednesday, July 14, 2010
Planning for retirement
According to the Westpac ASFA Retirement Standard, a retired Australian couple needs to earn more than $51,727 a year to live 'comfortably' or more than $28,080 a year if they want to live 'modestly'.
Investing in property is one way to help fund a comfortable retirement that allows you to pursue the interests, hobbies and activities of your choosing.
Here are 5 strategies for successfully using property investment to build wealth for retirement.
1. Think long term
Retirement strategies are all about investing money wisely over many years, building wealth through compound interest and re-investment. Think long term and have a realistic game plan that has built in buffers to ensure you remain in a comfortable position in future years.
2. Aim for capital gains
It is the capital gains that make property investing so attractive for retirement, so buy your property with capital growth in mind. This means choosing a home with resale potential that is of maximum appeal to tenants. Property experts often recommend new-built family homes because they usually have fewer maintenance costs, are attractive to the ideal tenant, and are tax effective for the investor.
3. Diversify
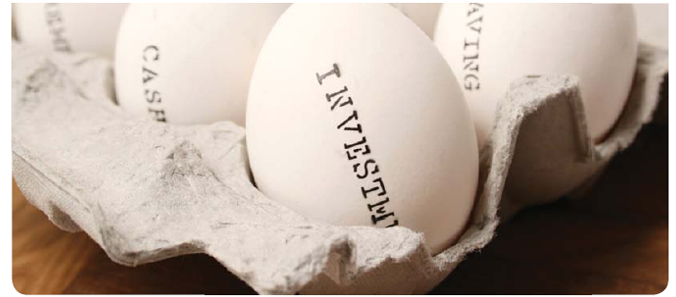
Property should play a big part in your investment portfolio but avoid putting all your eggs in the one basket. Diversify and spread your risk among a number of different sectors including property, shares or managed funds.
4. Consider taxation laws
Rental income may be taxed at a higher rate than superannuation unless you set up your own super fund and acquire property via your fund. Seek expert advice to best understand taxation laws and make the most of superannuation concessions.
5. Start now
It's never too soon to start planning for your future. While you are still working and have equity in your home, now is the time to use property investment as a way to optimise your financial security for the time when you plan to put your feet up!
For help on planning on retirement having an income stream during retirement, speak to one of the financial planners at Intellichoice on 1300 55 10 45 or email info@intellichoice.com.au.
Term deposits outperform shares
Cash investments have delivered far better returns to investors over the last three years than the sharemarket has. The average annual rate of return over the last three years from a one year term deposit has been 5.6%. The average annual return from ASX200 companies over the last three years has been minus 6.6%. Average dividend income for shares has been between 3.4% and 5.5%, which has been offset by some large capital losses.
Tuesday, July 13, 2010
Choosing a broker when you want to invest in shares

A full service broker is able to offer you advice on buying and selling shares and other exchange traded instruments such as options and CFDs, provide market research and structured tailored investments for your long term portfolios. As a full service broker is able to offer many services you would generally expect to pay a higher brokerage fee to buy and sell financial products.
On the other hand a non-advisory broker, commonly an online provider, offers no personal advice or recommendations and only provides a trade execution service. Consequently you would generally expect to pay a lower brokerage fee to buy and sell shares, and they are a popular choice for investors who are confident in making their own trading decisions.
Whether you are an active private trader or a long term investor there are many questions that you may need to ask before deciding which broker will best suit your needs.
What type of services do you require from a broker?
Full service offering research and advice, access to investment opportunities in company floats, and financial planning or an online service accessed via phone or internet, offering low cost trading, and straight through order entry.
How much do brokers charge?
Typically brokers will charge a flat fee for transactions below $10,000 and then a percent value of the trade for higher amounts. Often discounts can be negotiated for high volume clients.
Are regular newsletters or share market information available?
Both full service and non-advisory brokers will often provide daily and weekly newsletters recommending sectors and stocks that are performing. These can be provided either by email or by access via the broker’s website.
Do Brokers conduct workshops?
Brokers will often provide workshops on how to use their execution platform, and trade in different types of financial products.
When you select a broker you should ensure that you receive a Financial Service Guide (FSG), a Product Disclosure Statement (PDS) and a Client Agreement detailing the products and services that are being offered to you, and the applicable terms and conditions of trading, by that broker before you open your trading account.
For more information about investing in shares and other investments, speak to one of the financial planners at Intellichoice today on 1300 55 10 45 or visit www.intellichoice.com.au.
Wednesday, July 7, 2010
Creating an investment portfolio

- Are your investments going to be long term or short term?
- Are you looking for a return in the form of income and long term capital growth or a short term return in the form of a large capital growth?
- What is your tolerance to risk? Are you prepared to risk some of your investment capital for the opportunity to make higher returns?
If you are looking for income and long term capital growth then you should look at stocks that have a proven long term business model and pay good dividends. These stocks are referred to as Value Stocks and would be considered to have a lower risk profile. Their share prices gain over the long term and pay dividends every 6 months providing you with an income. Many stocks within the Infrastructure sector would be considered Value Stocks.
If you are looking for short term capital growth then you should consider stocks that are just starting their growth phase. These are usually new companies that are just starting production or expansion. These stocks are referred to as Growth Stocks and would be considered to have a higher risk. Many stocks within the Energy, Material and Health sectors would be considered Growth Stocks.
Don't put all your eggs in the one basket - investing evenly across Value and Growth Stocks can create a diversified investment portfolio with a medium risk profile. An educated investor can achieve both short and long term capital growth and create an ongoing income by receiving dividend payments.
The difference between a good and bad investment portfolio is always about education and knowledge. The educated investor will always look to buy stocks at discount prices and introduce simple hedging strategies to maintain the profitability of their investment portfolio during volatile times.
To find out whether investing in shares is right for you, speak to one of the financial planners at Intellichoice today on 1300 55 10 45 or visit www.intellichoice.com.au.
Monday, July 5, 2010
The other side of Lending – Mortgage Schemes

“I wish to get a better rate of return on my money and don’t really mind having an indirect exposure to property as the underlying asset class.'
That's roughly how a mortgage scheme (also called mortgage funds) works, except it involves three extra features:
- More than one person contributes money to the scheme;
- Investors' money is pooled together or used in a common enterprise for scheme members; and
- Scheme members give up day to day control over how the scheme operates.
In the past, most mortgage funds have operated successfully. Some, regrettably, got into disastrous financial trouble; either because the managers lacked the skill to manage mortgages, especially when some of the borrowers failed to pay, or they lent too much money on optimistic valuations or risky development properties. A handful of operators defrauded investors.
Watch your margin of safety
Risk in mortgage lending lies in the gap between the value of the property and how much of that value is being lent to the borrower (described as the loan-to-valuation ratio). The closer the amount lent to the value of the property, the higher the risk that you might lose part of your investment. A $60,000 loan for a property valued at $100,000 represents a conservative 60% loan-to-valuation ratio, but a $95,000 loan on the same property represents a much riskier 95% loan-to-valuation ratio.
What type of scheme can you choose?
Mortgage schemes, or mortgage funds can be set up in different ways. You can choose:
- Pooled mortgages, where all investors share in all the mortgages. You therefore take your share in all the income and spread the risks across all the mortgages that the scheme manages. LOW / MEDIUM RISK
- Contributory mortgages, where you choose which mortgage(s) you invest in. Your mortgage(s) may pay a different income from other mortgages in the scheme. Your risk depends on the quality of the borrowers to whom you have chosen to lend. MEDIUM RISK
- Debenture or mortgage companies, where you invest in shares or debentures issued by a company that invests in mortgages. Here, you are really becoming a shareholder in, or lender to, the company, which in turn owns the mortgages. Check whether the mortgages are pooled or linked to specific properties. HIGH RISK.
All scheme operators must treat investors honestly. At present you will find these types of scheme managers:
- Managers of registered schemes must operate the scheme through a public company that holds an Australian Financial Services Licence and comes under ASIC regulation. (You can check this licence free of charge through the ASIC website or contact the ASIC Infoline by email infoline@asic.gov.au or ring 1300 300 630.) The scheme must have a constitution, a compliance plan and a product disclosure statement that you can inspect. It must also have proper internal procedures for handling complaints, and be a member of an authorised external dispute resolutions scheme.
- Managers of industry supervised schemes must be supervised either by the Law Society of NSW or the Law Institute of Victoria. First, get a copy of the rules set by each body, then make sure any scheme you are considering is abiding by the rules before you invest.
- Directors of mortgage debenture companies must operate through a public company. They must act honestly and diligently, but require no licences or complaints schemes. The directors are free to choose whatever operating systems they like so long as they obey general company law.
- Managers of unregistered and unlicensed schemes must restrict their scheme to 20 people or less and must not be in the business of promoting schemes. Unregistered schemes are not regulated by anybody. You are on your own. Check everything and everybody involved.
Mortgage schemes may suit your needs and circumstances. Choose the scheme and the manager that suits your own knowledge and experience. If you possess no expertise in this area, you should seek appropriate financial advice.
For more information about mortgage schemes and whether they suit your needs, speak to one of the financial planners at Intellichoice today on +61 7 3624 1900 or email info@intellichoice.com.au. Alternatively, visit www.intellichoice.com.au.
Subscribe to:
Posts (Atom)